Two no-deposit vehicle finance offers can look almost identical when a salesperson highlights only the monthly instalment. That number is useful, but it is not enough to tell you which deal is safer or cheaper. A longer term, a balloon payment, fees, or a different interest rate can change the total cost substantially. You should also compare what each quote assumes about the vehicle, your credit profile, insurance, and repayment record. The strongest comparison is not the offer with the lowest advertised payment; it is the one you can afford consistently and understand completely. This guide gives you a practical way to put competing quotes side by side before choosing a lender or vehicle.
Compare the Financed Amount, Not Just the Instalment
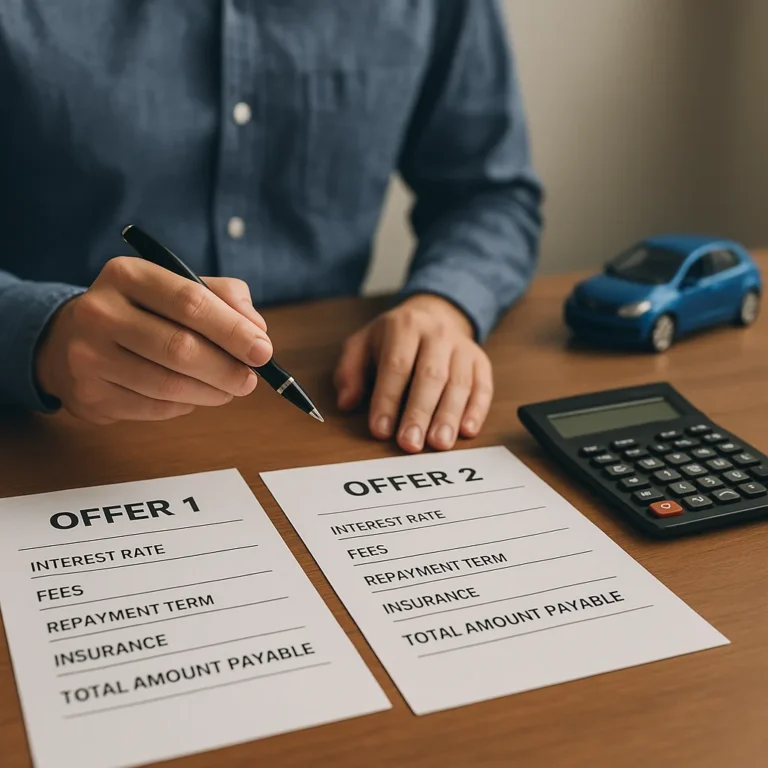
Start by requesting the same core figures from every provider. Record the vehicle price, deposit shown as zero, amount financed, interest rate, repayment term, monthly instalment, initiation fee, monthly service fee, and any balloon payment. If one quote leaves out a fee or uses a different vehicle price, the comparison is not fair. Ask whether the rate is fixed or linked to a benchmark, and whether the quoted instalment includes optional products. A lower repayment may simply reflect a longer term or a larger final balance. Put the information in a simple table, then compare matching assumptions before deciding which offer deserves closer attention.
Check Interest, Term, and Balloon Payment Together
Interest and term work as a pair, so avoid judging either figure alone. A lower rate may still produce a costly agreement if the repayment period stretches across many years. Conversely, a shorter term can reduce total interest but raise the monthly commitment beyond a comfortable level. Check whether the agreement includes a balloon payment and calculate how you would handle it at maturity: save monthly, refinance, or sell the car. Ask for the total amount payable over the full agreement, not just an annual percentage. If the lender cannot explain the calculation clearly, pause the comparison until you receive written figures.
Price the Vehicle Beyond the Finance Quote
Finance is only one part of the ownership bill. Add comprehensive insurance, fuel, servicing, tyres, licensing, tracking if required, and a realistic reserve for repairs. Some lenders may require specific insurance conditions, while a dealer may present add-on warranties or maintenance plans beside the finance quote. Treat each item separately and decide which is compulsory, useful, or optional. For example, an offer that saves R500 a month but comes with expensive insurance can be less affordable than a higher repayment with lower running costs. Build a monthly vehicle budget using your actual driving pattern, not an optimistic estimate based on occasional fuel spending.
Test Lender Conditions and Flexibility
Read the conditions that sit behind the headline price. Confirm whether early settlement, extra payments, payment-date changes, or refinancing carry charges. Check what happens after a missed instalment and whether the lender offers a process for financial difficulty. You should also verify the dealer’s role: a finance intermediary may send your application to several providers, but that does not mean every available offer is being shown. Ask who receives your personal information, which credit checks may be run, and whether you can take the written quotation away. Clear answers are part of a competitive offer, not an inconvenience.
Use a Side-by-Side Affordability Check
Before choosing, run a stress test using your household budget. Add the proposed repayment to essential expenses, existing credit, insurance, and a modest emergency contribution, then ask what would happen if fuel rose or income fell temporarily. Compare the result with your dependable take-home pay rather than a good month. Keep copies of both quotes and list every assumption that differs. A deal may be suitable even when it is not the cheapest on paper if it leaves useful breathing room and has understandable terms. If neither option remains comfortable after realistic costs, delaying the purchase is a financially valid result.
Where to continue your research safely
To keep researching, review National Credit Regulator consumer resources and compare which option makes the most sense for your situation.
Key criteria to compare before you decide
A good decision depends on more than a first impression. Compare total cost, timing, reputation, effort required, and the clarity of the offer conditions. When those criteria are visible together, it becomes easier to tell whether an option solves the problem or only looks attractive at first.
How to use this guide for your next step
Review the criteria before moving forward
Compare interest, fees, repayment terms, insurance, and the total amount payable calls for context, comparison, and patience. Use the points above as a practical checklist: revisit your goal, look for concrete signals, and move forward only when the choice fits your current needs.